The Role of Digital Identity in Cross-Border Remittances
Stay updated with us
Sign up for our newsletter
Cross-border remittances function as an essential element in the international financial system, allowing millions of people to transfer funds between different countries. The traditional remittance methods face challenges because they take a long time to process and generate high costs while requiring intricate procedures for regulatory compliance. Digital identity technology serves as the primary determinant that now impacts the progress of international payment systems.
Financial institutions and fintech platforms use digital identity systems to create smoother verification processes that protect their systems and enable customers to access their remittance services. Digital identity systems establish a direct link between enhanced identity verification processes and the core structure of modern international financial operations.
Why Identity Verification Matters in Remittances
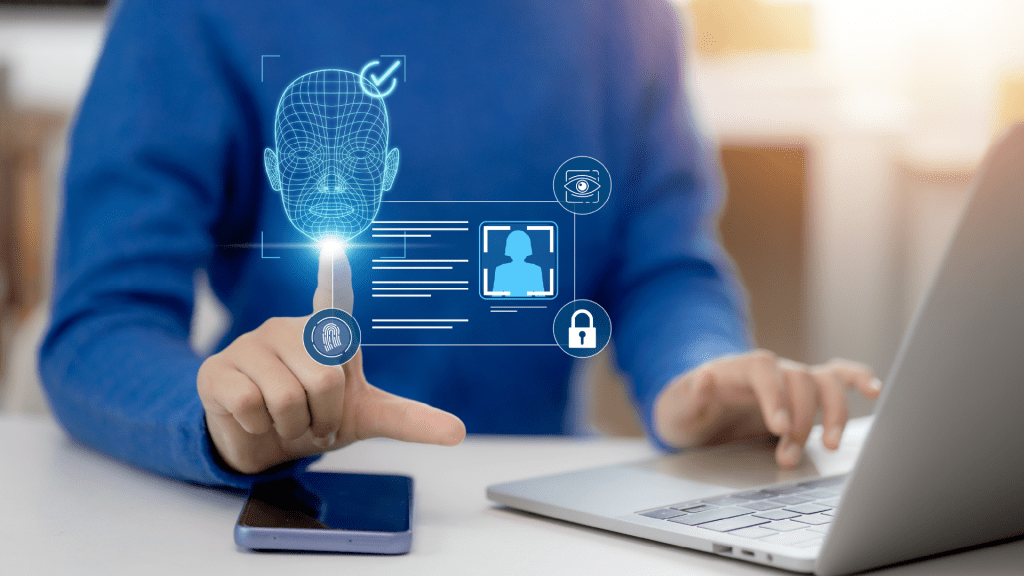
Identity verification plays a critical role in the functioning of cross-border remittances, as these transactions must comply with strict global regulations designed to prevent financial crimes such as money laundering and fraud. Financial institutions must implement Know Your Customer and Anti-Money Laundering protocols, which establish accurate identity validation as a mandatory requirement for moving forward with their transactions. Digital identity solutions are significantly improving this process by enabling faster, more reliable verification through digital documents, biometrics, and real-time data checks. The system decreases the time needed for onboarding while also reducing the chances of human mistakes that happen during manual verification processes.
The implementation of strong identity systems provides organizations with their best protection against unauthorized access and identity theft incidents. Fintech platforms achieve fund transfer security through their implementation of dual authentication systems, restricting access to verified users. This situation needs special attention because multiple intermediaries are involved during international operations. The process of identity verification creates reliable results that show users their transactions maintain security and legal requirements. Modern financial systems need strong identity systems, which function as basic requirements for maintaining operational transparency and system security while handling global money transfers.
Read More: Why Everyday Apps Are Becoming the New Banks
How Digital Identity Is Streamlining Remittance Flows
Remittance platforms use digital identity technology to improve their operations by making onboarding and transaction processing more efficient through reduced onboarding and transaction processing.
Faster Customer Onboarding
The traditional method of onboarding requires several days to complete the whole process. Users can complete registration and start their transactions within two minutes through digital identity verification, which uses digital documents and biometric authentication.
Seamless Cross-Platform Verification
The user can employ their digital identity to access different platforms without needing to verify each time. The system enables users to navigate easily between platforms while their transactions proceed at a faster pace.
Real-Time Transaction Processing
Digital identity verification enables platforms to conduct transactions at faster speeds because it eliminates the need for manual verification and compliance verification processes.
Expanding Financial Inclusion Through Digital Identity
Digital identity functions as a transformative element that enables financial institutions to reach more customers through its use in cross-border remittances. A significant portion of the global population remains unbanked, often due to a lack of formal identification required to access traditional financial services. Digital identity systems address this challenge by providing different verification options, such as biometric authentication and mobile credentialing, to help more users access financial services. The system enables users to send and receive money across international borders without needing to spend money on traditional banking services.
The process of combining digital identity with mobile platforms in developing regions establishes a simple process for users to access remittance services because most people use mobile devices to access online services. Users can securely verify their identity and complete onboarding processes while conducting real-time transactions, which do not require them to provide physical documents or attend in-person identity checks. The system enhances user experience through operational efficiency and provides users with enhanced authority to manage their financial transactions. Digital identity implementation shows scope to connect people with financial systems who have faced challenges in accessing these services for many years.
Enhancing Security With Advanced Identity Technologies
As remittance volumes increase, transaction security requirements become more critical.
- Biometric Authentication: Fingerprint scanning, facial recognition, and voice authentication technologies deliver extra security protection, which decreases identity theft risks.
- Decentralized Identity Models: The new decentralized identity frameworks let users manage their personal information while sharing only essential details needed for verification. The method improves security and privacy protection.
- Continuous Authentication: The system uses advanced technology to observe user activities and their remittance behavior, enabling it to detect unusual patterns that create an extra security barrier during the remittance process.
Read More: The Untapped Potential of Voice-Driven Banking Interfaces
Challenges in Implementing Digital Identity Systems
The process of establishing digital identity systems for cross-border remittances brings multiple obstacles as well.
- Fragmented Regulatory Environments: The lack of common international standards for identity verification and data privacy creates obstacles for different countries to create unified identification systems.
- Data Privacy Concerns: Users may be hesitant to share sensitive personal information, particularly across international platforms. The process requires both data protection and transparency to meet essential requirements.
- Interoperability Issues: Digital identity systems need to achieve universal effectiveness through their ability to function without issues across multiple platforms and legal systems. Governments, financial institutions, and technology providers need to work together to achieve this level of system interoperability.
Conclusion
Digital identity is changing cross-border remittance systems because it enables faster verification, better security, and wider financial service access. Digital identity systems reduce friction in onboarding and transaction handling, which results in better access to international money transfer services. Worldwide payment systems are developing new methods that will use digital identity to create safe and open payment networks that can scale according to the requirements of online communication networks.